
 By Frank Mwiti, Chief Executive Officer, Nairobi Securities Exchange
Africa may be the most persistently mispriced growth story in global finance. Returns on equity across the continent’s banking sector reached 19 percent in 2024, nearly double the global average of 10 percent, while banking revenues crossed the US$100-billion threshold for the first time. Yet Africa continues to attract only a marginal share of global institutional capital. The continent represents approximately 3 percent of global gross domestic product (GDP) and 17 percent of the world’s population; the International Monetary Fund (IMF) has projected it to be the fastest-growing region through 2029—yet it holds barely 1 percent of global sovereign-bond allocations and less than 1 percent of global equity-market capitalisation. (Africa’s equity-market capitalisation reached $561 billion by end-2024, representing less than 1 percent of the approximately $110 trillion in global equity-market capitalisation.) Global institutional portfolios now exceed $300 trillion, with more than 70 percent of equity and bond benchmark exposure concentrated in North America and Europe.
This is not a failure of performance. It is a failure of pricing. For too long, global capital has assessed Africa through frameworks that are outdated, aggregated and structurally biased toward caution. But what is now unfolding is not a cyclical rebound. It is a structural repricing. As market infrastructure strengthens, digital rails expand, and a deeper body of empirical evidence challenges long-held assumptions, Africa is moving from the margins of portfolio construction to the centre of strategic allocation.
The real story, therefore, is no longer whether Africa can perform. It is whether the world’s allocation models can keep up.
In that shift lies a larger truth: Africa is no longer merely becoming investable. It is becoming increasingly difficult to ignore. The real story, therefore, is no longer whether Africa can perform. It is whether the world’s allocation models can keep up.
The mispricing of a continent
The persistent underallocation to Africa is often justified by a familiar narrative: high risk, low transparency and limited liquidity. Yet the evidence increasingly tells a different story.
Across the continent, financial-sector performance has materially outpaced global benchmarks. On a constant-currency basis, African banking revenues grew by around 17 percent per year between 2020 and 2024, far faster than the global average, with revenues rising from $83.4 billion to approximately $99 billion over that period. But the more consequential story is now visible in capital markets.
Across exchanges from the Johannesburg Stock Exchange (JSE) to the Egyptian Exchange (EGX) and the Nairobi Securities Exchange (NSE), equities have delivered strong US-dollar-adjusted returns while continuing to trade at meaningful discounts to global peers. In Kenya, valuations near 7.8-times earnings, roughly a 30-percent discount, coexist with dividend yields above 5 percent (as recorded in January). Meanwhile, African sovereign and corporate bonds continue to offer 10 to 15 percent USD yields, often misaligned with realised default experience.
The disconnect is structural—and now empirically documented. The Global Emerging Markets Risk Database (GEMs) Consortium, a joint initiative of multilateral development banks (MDBs) and development finance institutions (DFIs) spanning 41 years of data, released updated statistics in October 2025 that directly challenged prevailing risk assumptions. Over a 41-year period across 167 sovereign EMDE (emerging markets and developing economies) borrowers, the annual default rate averaged just 0.77 percent, with recovery rates on sovereign and sovereign-guaranteed lending averaging 95.1 percent. For private-sector lending, default rates averaged 3.54 percent across more than 10,000 entities in 169 countries—comparable to default rates of private firms in advanced economies—while recovery rates of 72.9 percent surpassed global benchmarks. Most significantly, analysis shows that default rates per rating category for African sovereign debt are similar to those for the global sovereign portfolio, suggesting that market spreads for African sovereigns incorporate considerations well beyond the credit risks reflected in ratings.
Africa is not underinvested because it is too risky. It is underinvested because risk is poorly measured.
From perception to production: The real economy is already repricing Africa
The strongest evidence of mispricing does not come from models. It comes from reality.
In Nigeria, the Dangote Petroleum Refinery, a $20-billion investment with a nameplate capacity of 650,000 barrels per day, is the world’s largest single-train refinery. It is not merely meeting domestic demand; it is reshaping regional energy trade flows and reducing structural import dependence. Alongside it, the Dangote Fertiliser Plant produces approximately three million tonnes annually, positioning it among the largest fertiliser facilities globally.
Across Africa, the growth story is equally compelling—and now supported by hard forecasts. The IMF has projected Sub-Saharan Africa’s GDP growth at 4.1 percent in 2025, with the continent forecasted to record an average growth of 4.3 percent in 2026, the fastest of any region globally. Africa is expected to outpace all other regions in real GDP growth from 2026 to 2029, maintaining a steady GDP growth rate of 4.3 to 4.4 percent, while Europe is forecasted to decelerate to 1.5 percent by 2029. Countries including Benin, Côte d’Ivoire, Ethiopia, Rwanda and Uganda are consistently among the world’s fastest-growing economies, with growth rates frequently in the 6-to-8-percent range. Meanwhile, the African Continental Free Trade Area (AfCFTA) brings together a unified market of 1.4 billion people with a combined GDP exceeding $3.4 trillion, projected to reach $7 trillion by 2035.
Demographic fundamentals underpin this trajectory. Africa’s population grew by more than 2 percent per year between 2020 and 2025, while the working-age population expanded by nearly 3 percent annually—the fastest of any region. At the same time, long-term credit datasets from the GEMs Consortium confirm that African sovereign borrowers have historically exhibited default rates comparable to similarly rated peers globally, particularly across full credit cycles.
This creates a striking asymmetry: While Africa’s industrial capacity is scaling rapidly, its growth rates are the highest in the world, and default outcomes are proving to be more stable than commonly perceived, capital-allocation frameworks remain anchored in outdated assumptions. Africa is not waiting to be repriced; it is already being repriced in the real economy. Capital markets do not lead structural change; they lag behind it, and in Africa, they are now beginning to catch up.
Liquidity: From constraint to capability
Liquidity has long been the decisive objection to allocating capital to Africa. That objection is eroding.
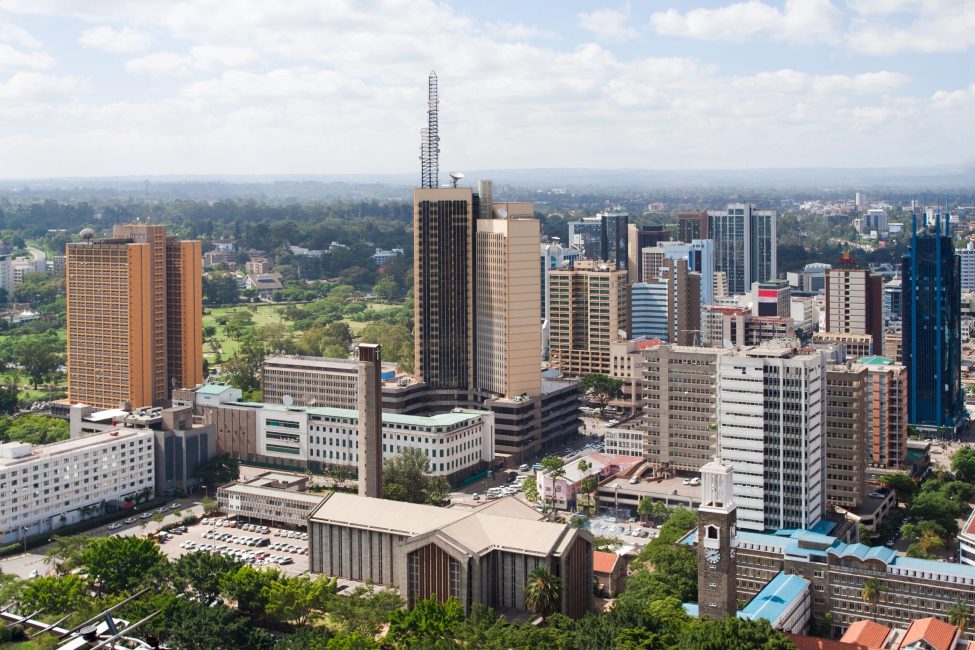
At the Nairobi Securities Exchange, this shift is already visible in hard numbers: bond-market turnover exceeding $3 billion in a single month, over $5 billion traded in the first two months of 2026 alone, and equity turnover rising sharply, supported by domestic participation. More importantly, market participation itself is being transformed. Through platforms such as Ziidi Trader, developed in collaboration with Safaricom and winner of the GSMA GLOMO Award for mobile financial services innovation, retail investors are no longer peripheral. They are becoming structural contributors to market liquidity, with digital channels accounting for a majority of trading activity in certain periods. At the same time, the Nairobi Securities Exchange is advancing Direct Market Access (DMA) frameworks, securities lending and borrowing infrastructure and has expanded multi-asset product capabilities. This is not just liquidity improving. It is market architecture being rebuilt for scale.
Across the continent, similar shifts are evident: The Johannesburg Stock Exchange continues to anchor institutional liquidity, the Egyptian Exchange is attracting renewed foreign participation, and the Nigerian Exchange Group (NGX) is seeing capital return following FX (foreign exchange) reforms. Liquidity is no longer the constraint it once was.
From markets to instruments
The transformation is not only in volume but also in what investors can actually access.
At the Nairobi Securities Exchange, recent developments illustrate this shift clearly: oversubscribed green bonds with demand exceeding 170 percent, asset-backed securities linked to infrastructure and housing, USD-denominated REITs (real estate investment trusts) introducing hard-currency exposure, and cross-listed global instruments expanding investor reach. These are not incremental innovations. They are signals that African markets are beginning to offer the building blocks of modern portfolio construction.
Across Africa, this evolution is accelerating: structured debt markets in Egypt and Morocco, deep derivatives ecosystems in South Africa and expanding sovereign and corporate issuances across West Africa. Capital does not allocate to narratives. It allocates to instruments. And those instruments are now emerging.
Acknowledging the headwinds
None of this is without risk, and intellectual honesty requires naming the structural headwinds that remain.
The McKinsey data, while striking, carries an important caveat: Africa’s strong banking returns have been driven in part by favourable external conditions—elevated interest rates, loan repricing and foreign-exchange gains—rather than by improvements in operational efficiency. African banks’ cost-to-assets ratio remains at 2.6 percent, double the global average of 1.3 percent. Institutional-investor depth remains shallow: Insurance penetration across Africa stands at 3.5 percent of GDP, half the global average, and pension-fund assets are equivalent to only 23 percent of GDP, compared with 34 percent globally. And the external environment is not benign: Tariffs on African exports to the United States have increased, preferential access under the African Growth and Opportunity Act (AGOA) has expired, and projected declines in foreign aid leave several lower-income economies particularly exposed.
But these are the conditions from which repricing begins—not the conditions that prevent it. The question is not whether Africa faces structural challenges. Every frontier and emerging market does. The question is whether the trajectory of improvement in market infrastructure, transparency and performance is sufficient to compress risk premiums over time. On that measure, the evidence is increasingly difficult to dismiss.
Digital finance: The next acceleration layer
Africa’s capital markets are poised for a leap, not merely through incremental reform, but also by embracing digital financial infrastructure.
The integration of virtual-asset exchanges, tokenisation of real-world assets, stablecoin-based settlement rails and robust digital-asset custody frameworks will drive a new wave of acceleration—transforming how capital flows and how assets are accessed and traded while fundamentally redefining liquidity and market efficiency across the continent.
These developments are still emerging across African markets, but their direction of travel is clear. When integrated within regulated exchange environments such as the Nairobi Securities Exchange, they have the potential to lower issuance and transaction costs, expand global investor participation, enable fractional ownership at scale and improve liquidity and settlement efficiency. This is not a replacement of capital markets. It is an acceleration of them.
Africa’s readiness for this transition is already visible. Globally, four African countries—Nigeria, Ethiopia, Kenya and South Africa—rank among the top 30 in cryptocurrency adoption, underscoring the continent’s openness to emerging digital technologies in finance.
Information and the repricing mechanism
Ultimately, capital follows conviction, and conviction follows clarity.
Africa’s historical challenge has been informational compression: markets grouped together, risks generalised and opportunities overlooked. That constraint is dissolving. As transparency improves and performance becomes harder to ignore, investors are beginning to differentiate rather than generalise. That is when repricing happens.
Critically, the data infrastructure to support this differentiation is now emerging. The GEMs Consortium’s release of granular default and recovery statistics by region, sector and country provides institutional investors with the empirical foundation to price African risk with precision, rather than through broad-brush risk premiums. Foreign direct investment (FDI) inflows to Africa, while still constituting less than 5 percent of the global total, are increasingly diversifying away from extractive industries toward renewable energy, technology and manufacturing. (FDI inflows to Africa have constituted less than 5 percent of global FDI over the past decade. Africa historically offers higher average FDI returns than other developing regions.) (FDI growth has been driven by sectors such as renewable energy, software and IT [information technology] services, and business services.) These shifts are not merely quantitative. They reflect a qualitative transformation in how the global investment community understands the continent.
Africa is not short of opportunity. It is short of being correctly understood, and capital will follow the moment that changes.
Conclusion: The quiet repricing
Africa is not short of opportunity. It is short of being correctly understood, and capital will follow the moment that changes.
Africa’s repricing is already underway.
Not because sentiment has shifted. But because the foundations of allocation are changing: real economies are scaling, markets are deepening, instruments are expanding, access is improving, and digital infrastructure is emerging. The empirical record—from GEMs default data to IMF growth forecasts to McKinsey banking revenue analysis—is building a body of evidence that makes structural underweighting increasingly difficult to justify on fiduciary grounds.
The opportunity is not in discovering Africa. It is in recognising that it is already being repriced and positioning before that recognition becomes consensus.
Disclaimer
The views expressed in this article are his own and do not necessarily represent the official position of the NSE or its subsidiaries.
Frank Mwiti is Chief Executive Officer of the Nairobi Securities Exchange (NSE), bringing more than 24 years of international experience across investment banking, capital markets and management consulting. He has held senior positions at UBS, Deutsche Bank, PwC and EY, and currently chairs several global and regional boards. He also holds credentials from MIT, an LL.B degree and is a Certified Public Accountant (CPA).